Personal Finance Tips 2026: 10 Habits That Build Wealth
Good personal finance tips rarely involve a secret trick or a hot stock; they come down to a handful of repeatable habits that compound quietly over years. In 2026, with prices still shifting and interest rates in flux, the people who feel calm about money are usually the ones running a simple system rather than chasing the latest fad. This guide lays out ten habits you can start this week.
Think of these less as rules and more as a framework. Adopt the ones that fit your life, automate what you can, and let time do the heavy lifting. Small, consistent moves beat dramatic one-off gestures every single time.
Start With a Budget That Survives Real Life
A budget only works if you will actually keep it, so begin with something forgiving. The 50/30/20 split is a reliable starting point: half of take-home pay for needs, thirty percent for wants, and twenty percent for saving and debt.
The percentages are a guide, not a cage. If rent eats more than half your income, adjust the other buckets rather than abandon the plan. The point is to give every dollar a job before the month begins.
Track before you cut
Spend two weeks simply recording where money goes before slashing anything. Most people discover a surprise category, often food delivery or forgotten subscriptions, that frees up cash without any real sacrifice.
Build an Emergency Fund First
Before investing or aggressively paying debt, stash a starter emergency fund. Even one month of expenses turns a flat tire or medical bill from a crisis into an inconvenience.
- Open a separate high-yield savings account so the money is out of sight.
- Automate a small weekly transfer, even just a few dollars.
- Build to one month of costs, then keep climbing toward three to six.
- Only touch it for genuine emergencies, then refill it promptly.
Keeping this cushion in an insured account matters. You can confirm a bank’s insurance status directly with the FDIC before you deposit.
What Are the Best Personal Finance Tips for Beginners?
If you are just starting, resist the urge to optimise everything at once. The highest-impact personal finance tips for beginners are refreshingly basic, and doing them imperfectly beats planning them perfectly.
- Spend less than you earn, and widen that gap over time.
- Automate savings so you never rely on willpower.
- Pay off high-interest debt before chasing investment returns.
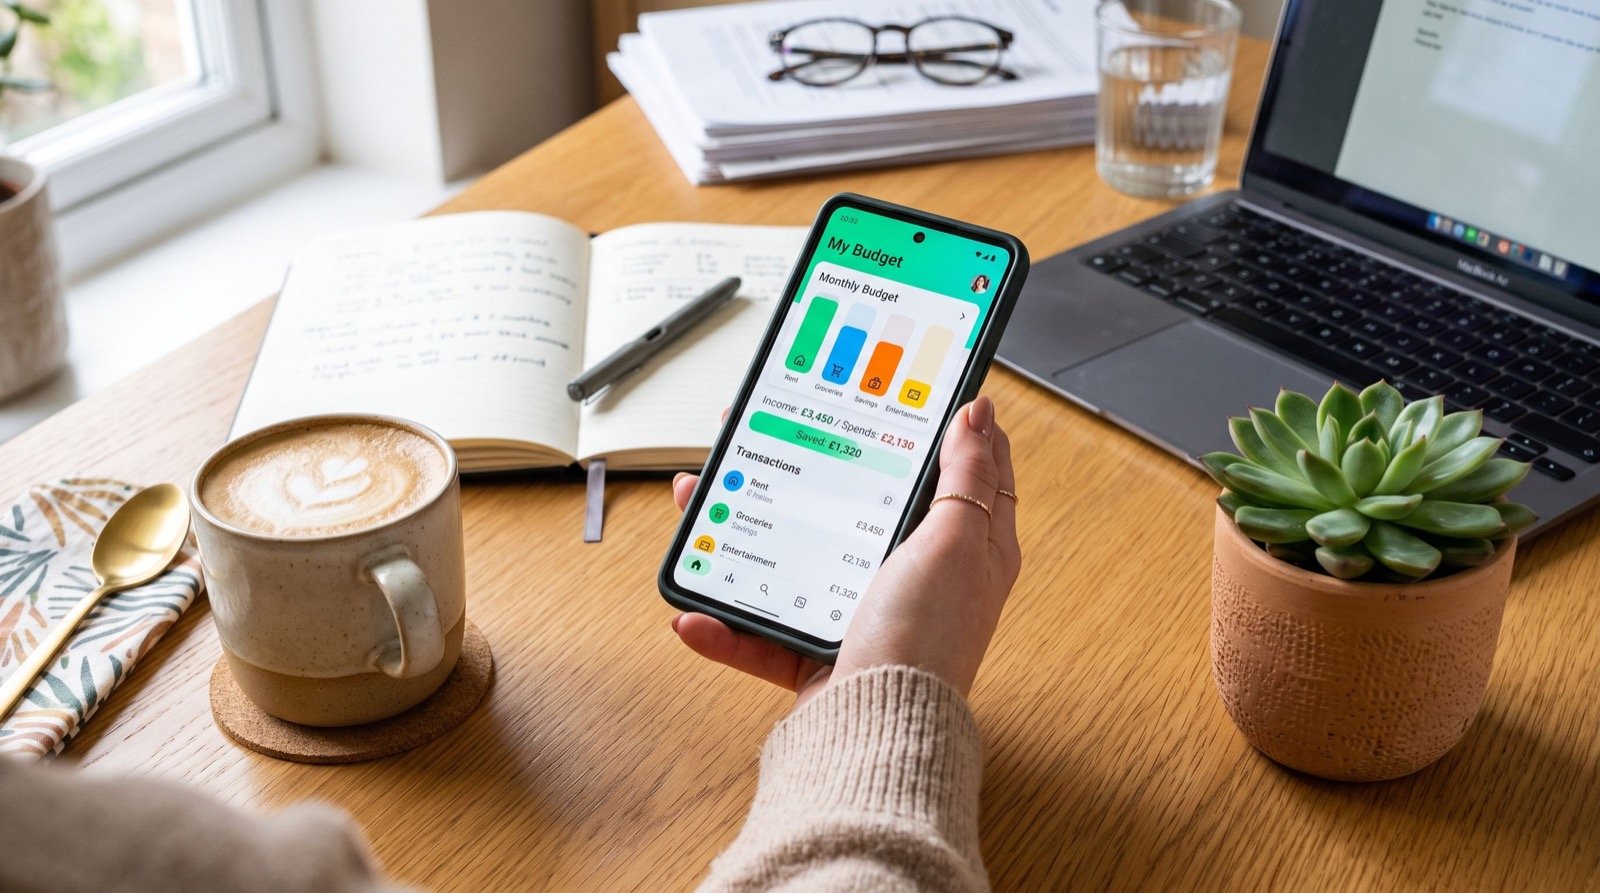
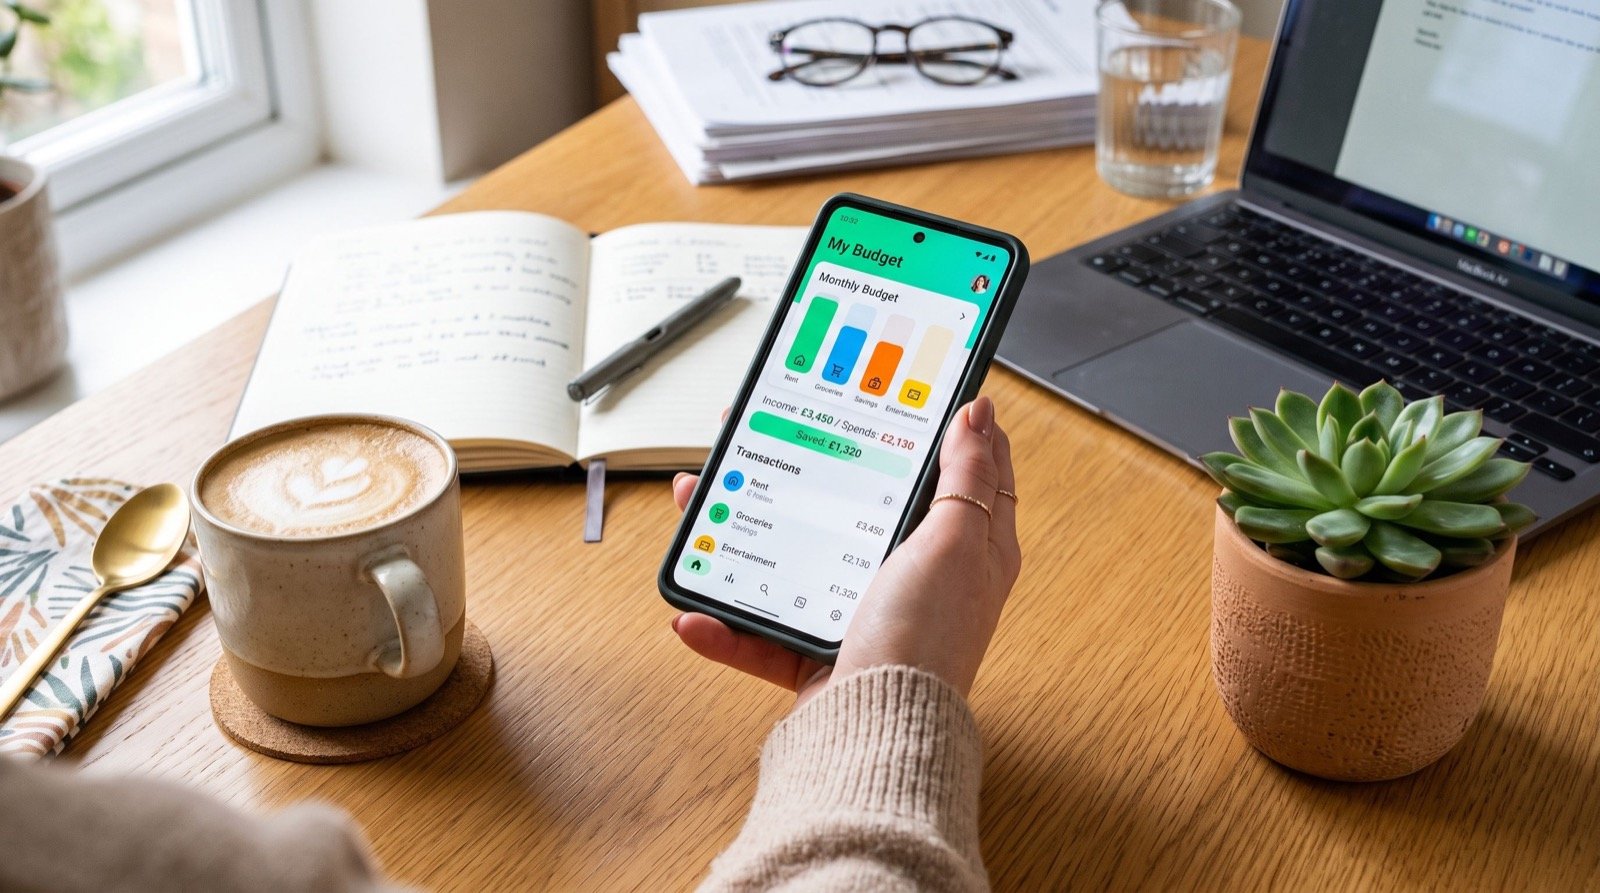
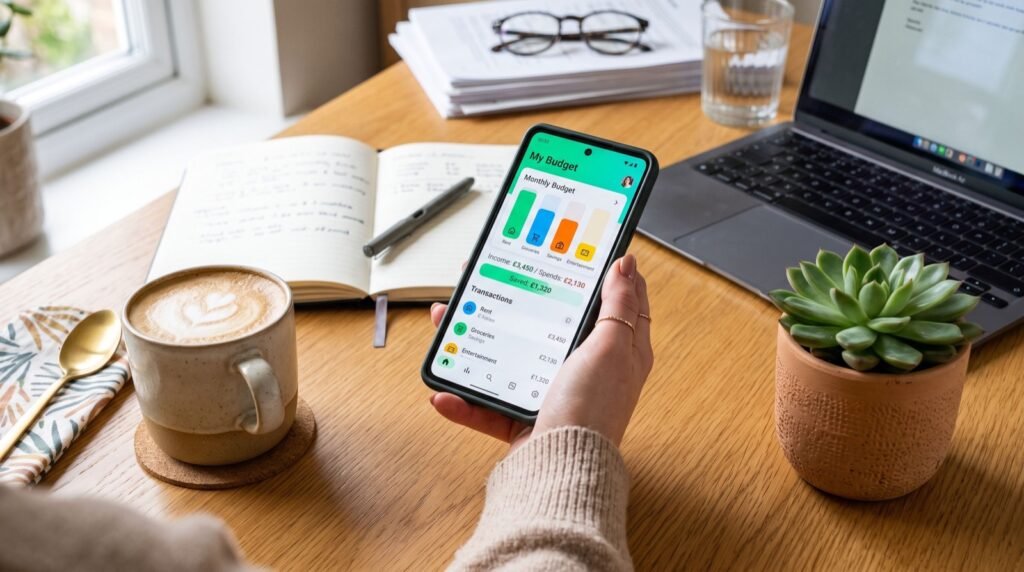
- Use free digital tools to track spending without manual effort.
- Review your plan once a month for fifteen minutes.
Digital tools make this far easier than it was a decade ago. A simple Cash App guide can show you how a single wallet handles sending, saving, and round-ups in one place.
Tackle Debt With a Clear Method
Debt repayment feels chaotic until you pick a method and commit. Two approaches dominate, and both work; the best one is the one you will stick with.
| Method | How It Works | Best For |
|---|---|---|
| Avalanche | Pay highest interest rate first | Saving the most money |
| Snowball | Pay smallest balance first | Staying motivated |
| Consolidation | Combine into one lower-rate loan | Many high-rate debts |
The avalanche saves the most in interest, while the snowball delivers quick wins that keep you going. There is no shame in choosing motivation over math if that is what gets you to zero.
Automate, Then Invest for the Long Run
Once debt is under control and your emergency fund is solid, direct attention to growth. Automation is again your friend: schedule contributions to retirement or index funds so investing happens before you can spend the money.
Keep it simple and steady
Low-cost, diversified index funds suit most people better than trying to pick winners. Contribute regularly, ignore short-term noise, and let compounding work across decades. The government’s plain-language investing hub at Investor.gov is a trustworthy place to learn the basics without a sales pitch.
One hard-won insight: your savings rate matters more than your investment returns in the early years. Doubling what you set aside does more for a young saver than chasing an extra percentage point of return.
Protect Your Progress
Wealth you build can be eroded by fraud, neglect, or a single bad month. Review your accounts monthly, freeze your credit when you are not applying for anything, and keep insurance adequate for your stage of life.
For bigger decisions like a mortgage, business loan, or tax strategy, it is wise to consult dependable specialists rather than guessing. A single well-timed piece of professional advice can outweigh years of small optimisations.
A simple monthly ritual
- Reconcile your accounts and categorise spending.
- Confirm automated savings and bill payments went through.
- Check your credit report for anything unexpected.
- Adjust next month’s plan based on what you learned.
Lifestyle Choices That Quietly Shape Your Finances
Spreadsheets get the attention, but the biggest levers are often lifestyle decisions made once and felt for years. Where you live, what you drive, and how you handle recurring commitments usually matter more than trimming small daily treats.
Guard against lifestyle creep, the slow habit of spending more every time you earn more. A raise is most powerful when part of it is redirected to savings before it ever reaches your checking account, so your costs rise slower than your income.
Small shifts, large impact
Negotiate recurring bills once a year, buy reliable rather than flashy, and delay big purchases by a week to filter out impulse. None of these feel dramatic in the moment, yet together they can free up a meaningful share of your income over a decade without any sense of deprivation.
Frequently Asked Questions
What is the easiest personal finance tip to start with today?
Automate a small, recurring transfer into a separate savings account. It removes willpower from the equation and quietly builds a cushion that protects every other goal you set.
How much should I keep in an emergency fund?
Aim for three to six months of essential expenses once you are established. Start smaller, though; even one month of costs dramatically reduces financial stress and keeps a setback from becoming a spiral.
Should I pay off debt or invest first?
Clear high-interest debt, especially credit cards, before investing, because the guaranteed interest you avoid usually beats uncertain market returns. Keep a small emergency fund alongside so you do not reach for the card again.
Do budgeting apps really help?
Yes, mainly by making your spending visible with little effort. Awareness alone changes behaviour, and automation features help you save and pay bills on time without constant attention.
Conclusion: Small Habits, Big Results
The most powerful personal finance tips are unglamorous: budget forgivingly, build a cushion, kill expensive debt, automate savings, and invest steadily for the long run. None of it requires luck, only repetition.
Pick two habits from this list and start them this week, then layer on the rest as they become routine. Ready to take control in 2026? Set up your first automatic transfer today and let consistency do the rest.