Personal Finance Tips for 2026: 12 Habits That Build Real Wealth
Strong personal finance tips do not require a finance degree, a six-figure salary, or complicated spreadsheets. They require consistency. In 2026, with prices still shifting and interest rates in flux, a few durable habits will protect your money better than any hot stock tip. I have coached friends and family through tight budgets and comfortable ones, and the same core principles work at every income level.
This guide skips the jargon and focuses on actions you can start today. Each tip stacks on the last, so by the end you will have a simple, repeatable system.
Start With the Foundation: Budget and Track
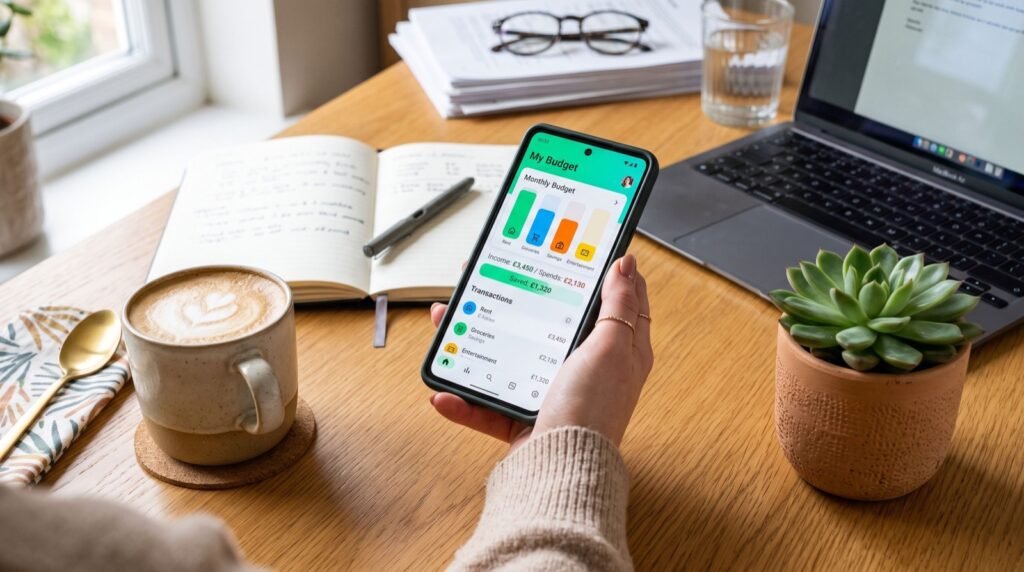
You cannot manage what you cannot see. The first step is tracking every dollar for one full month. Most people discover small, recurring leaks, such as forgotten subscriptions or impulse purchases, that quietly drain hundreds each year.
Once you see the pattern, build a budget that reflects reality instead of wishful thinking. The popular 50/30/20 framework splits income into needs, wants, and savings. Adjust the ratios to fit your life, but keep the structure.
The 50/30/20 Starting Point
- 50% needs: housing, utilities, groceries, transport, minimum debt payments.
- 30% wants: dining out, entertainment, hobbies, travel.
- 20% savings and debt payoff: emergency fund, investments, extra debt payments.
For free, unbiased education on budgeting basics, the government resource at MyMoney.gov offers worksheets and checklists worth bookmarking.
Personal Finance Tips for Building a Safety Net
An emergency fund is the single best stress reducer in personal finance. Aim for a starter cushion of one month of expenses, then grow it to three to six months over time. Keep it in a separate high-yield savings account so it earns interest and stays out of sight.
Automate the transfer on payday. When saving happens before you can spend, the money accumulates without effort. Even a modest weekly amount compounds into meaningful security within a year.
Tackling Debt Strategically
High-interest debt, especially credit cards, erodes wealth faster than almost anything else. Two proven payoff methods work well:
- Avalanche: pay the highest-interest debt first to save the most money.
- Snowball: pay the smallest balance first for quick psychological wins.
Pick the method that keeps you motivated. The best strategy is the one you will actually follow to the finish line.
Grow Your Money With Smart Tools
Saving protects you, but investing grows you. Thanks to compound interest, money invested early has decades to multiply. Low-cost index funds remain a reliable choice for beginners because they spread risk across hundreds of companies.
Modern apps make this easy. For a closer look at platforms that handle transfers, saving, and spending, this Cash App guide explains how to move money safely while you build your system.
| Goal | Best Vehicle | Why It Works |
|---|---|---|
| Emergency fund | High-yield savings | Safe, liquid, earns interest |
| Short-term goal | Money market or CD | Low risk, predictable return |
| Retirement | 401(k) or IRA | Tax advantages, compounding |
| Long-term growth | Index funds | Diversified, low fees |
Protect Your Credit Score
Your credit score shapes the interest rates you pay on everything from cars to mortgages. Pay bills on time, keep credit utilization below 30 percent, and check your report regularly for errors. A strong score can save you thousands over a lifetime.
Which Personal Finance Tips Matter Most for Beginners?
If you only adopt three habits, make them these: track your spending, automate your savings, and eliminate high-interest debt. Everything else builds on that base. Momentum matters more than perfection, so start messy and refine as you go.
For curated guides and ongoing personal finance tips, bookmark a trusted resource and revisit it when a new life stage brings new money questions.
When larger decisions arise, such as a relocation or a major purchase, consulting dependable specialists helps you plan the costs before you commit.
A Tip From the Trenches
Name your savings goals. A fund labeled “Italy 2027” or “car repair” is far harder to raid than a generic account. This small psychological trick dramatically improves follow-through.
Avoiding the Lifestyle Creep Trap
Here is a lesson that catches many people by surprise. As income rises, spending quietly rises with it, a pattern known as lifestyle creep. A raise feels great, yet within months the extra money vanishes into bigger subscriptions, nicer dinners, and upgraded gadgets.
The fix is simple but powerful. Each time your income grows, direct at least half of the increase straight to savings or investments before you adjust your lifestyle. You still enjoy a reward, but your future self gets the larger share.
Practice mindful spending too. Before any non-essential purchase over a set amount, wait 24 hours. The pause breaks the impulse cycle and reveals whether you truly want the item or simply crave a quick dopamine hit.
- Automate a savings bump every time you get a raise.
- Audit subscriptions quarterly and cancel what you no longer use.
- Use the 24-hour rule for discretionary buys.
- Reward progress with small, planned treats so the plan stays sustainable.
Frequently Asked Questions
How much should I save each month?
Aim for 20 percent of your income toward savings and debt payoff, but start with whatever you can sustain. Even 5 percent builds the habit, and you can increase the rate as your income grows or debts shrink.
What is the fastest way to pay off debt?
The avalanche method saves the most money by targeting high-interest balances first. If you need motivation, the snowball method clears small debts quickly for momentum. Both work when applied consistently.
Do I need an emergency fund before investing?
Build at least a one-month starter cushion first, then invest while continuing to grow the fund. An emergency fund prevents you from selling investments at a loss during a crisis.
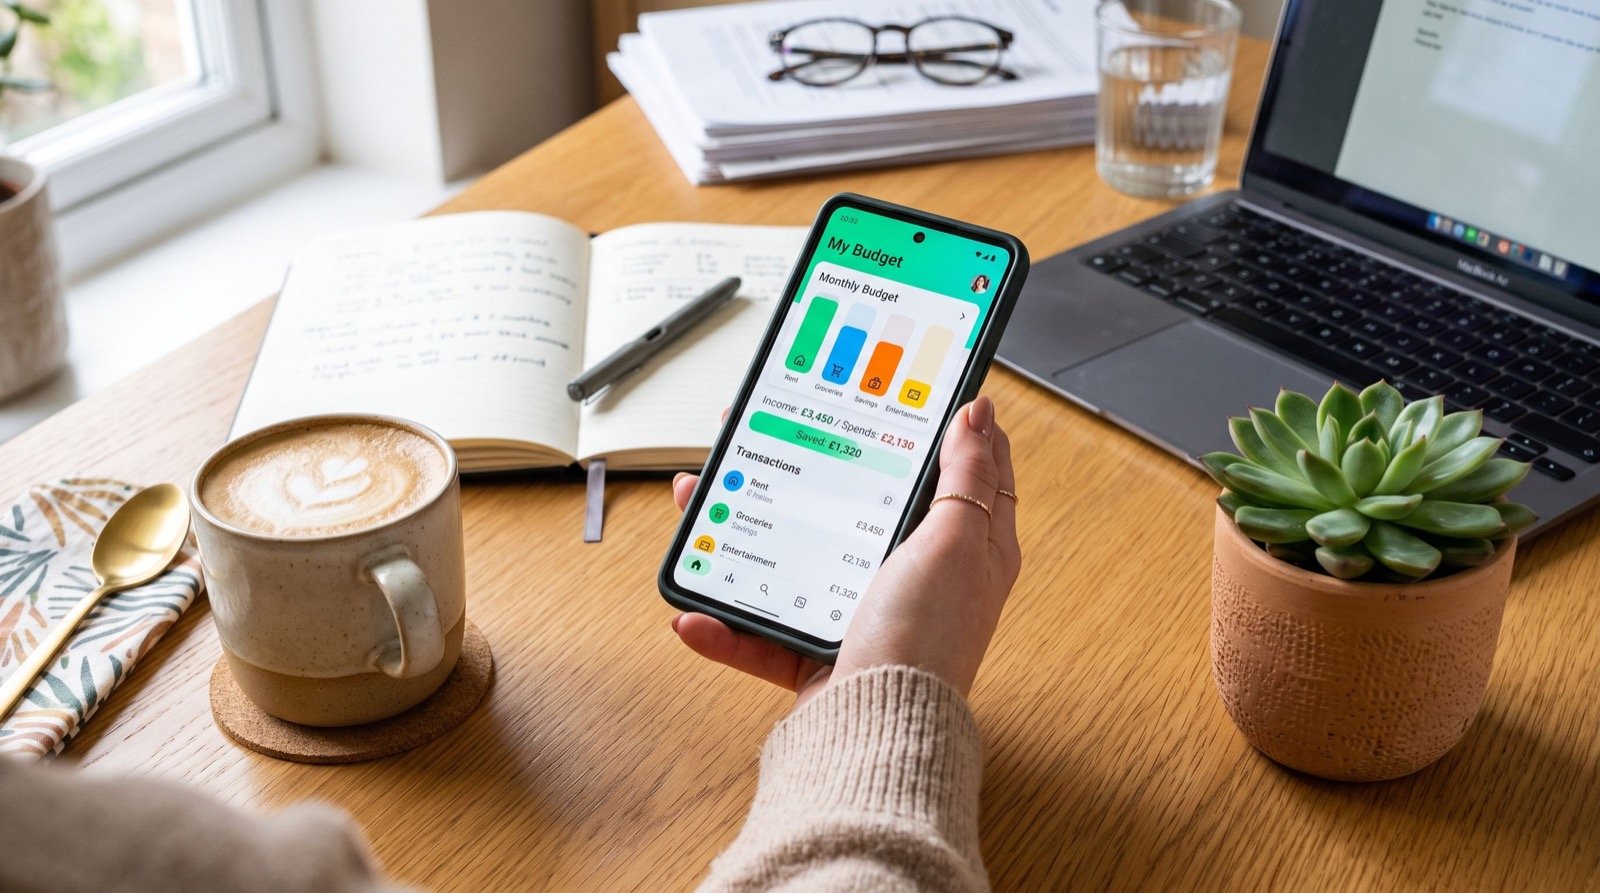
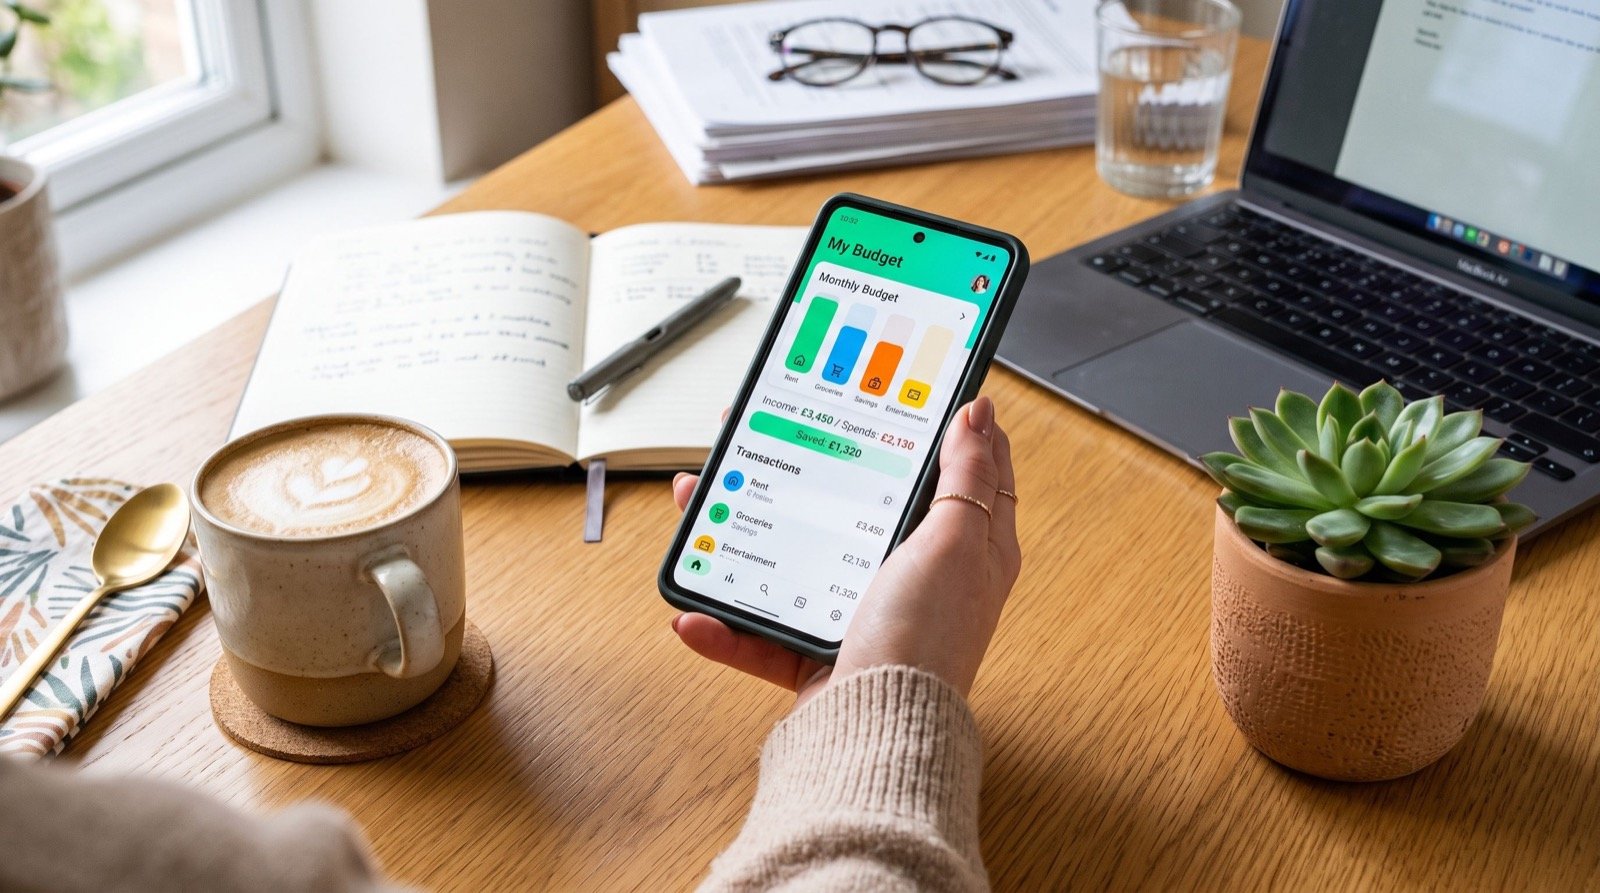
Are budgeting apps worth it?
Yes, for most people. They automate tracking, flag overspending, and keep goals visible. Choose one with strong security and a free tier before paying for premium features.
Conclusion
These personal finance tips prove that wealth is built through boring, repeatable habits rather than lucky breaks. Track your money, automate your savings, crush high-interest debt, and let compound interest do the heavy lifting over time. Pick one habit to implement this week, then layer on the rest as each becomes second nature. Your future self will thank you, so take the first step today and open that high-yield savings account.